Key Takeaways
- A narrated phone video of a typical apartment takes about 20 minutes; photo-and-spreadsheet inventories usually take a full weekend.
- Renters contents limits are often $15,000 to $50,000, because a landlord's policy covers the building and not your belongings.
- Open every closet, drawer and cabinet, zoom in on serial numbers, then store the video in cloud storage.
- Jewelry, firearms, cash and collectibles often face category sub-limits of a few thousand dollars; scheduling requires appraisals or receipts.
What this guide covers: why an inventory shapes both your contents payout and your temporary housing, the 20-minute video method, a room-by-room checklist of what people forget, how sub-limits treat valuables, and a worked example of what the numbers look like with and without one.
There are two versions of you: the one reading this on a quiet evening, and the one standing in a parking lot watching firefighters work, trying to remember what was in the hall closet. The second version can't make an inventory anymore. The first one can, tonight, in about 20 minutes.

Why Does a Home Inventory Decide How Your Claim Goes?
A home inventory for insurance touches two separate checks after a loss: your personal property (contents) payout and the Additional Living Expenses (ALE) budget that pays for temporary housing.
On the contents side, your carrier typically asks for an itemized list of what was damaged or destroyed, with the item, brand, age, and approximate value. Many policies pay actual cash value first, then release recoverable depreciation as you replace items. That whole process runs on documentation.
Your payout is built from the proof you can produce. An item you can't recall and can't substantiate effectively never existed on paper, and a from-memory list written in a hotel room three days after a fire is always shorter than the truth.
Renters feel this hardest. Your landlord's policy covers the building, and your belongings live only on your renters policy. Renters contents limits are typically modest, often in the $15,000 to $50,000 range, and under-documenting a small limit means leaving a bigger share of it unclaimed. If you rent, pair this guide with does renters insurance cover temporary housing.
Less obviously, the same footage documents how your household lives: how many bedrooms, a crib, a dog, a home office. That context shapes what "comparable housing" means when your adjuster scopes loss of use coverage, which is why a good inventory quietly speeds the housing side of the claim too.
On how easily policy coverage gets misread before a loss:
The insurance is often misunderstood by its purchasers; for example, many believe that mold is covered when it is not a standard coverage.
Wikipedia: Home insurance
What Happens After a Loss With No Inventory?
Without an inventory, a contents claim typically stretches weeks longer, because every item must be recalled, listed, priced, and justified after the fact while you're also living out of bags.
- First 48 hours: the adjuster asks for your contents list. You have memory, adrenaline, and whatever survived on your phone.
- Week one: you rebuild the list from card statements and online order histories while also hunting for housing and keeping kids in their school routine.
- Weeks two through six: the list trickles in piecemeal. The first actual-cash-value check is small because the list is.
- Months two through four: you keep remembering items after the claim has moved on, and each supplement request takes another round of review.
- Closeout: forgotten items and unclaimed recoverable depreciation stay with the carrier instead of coming to you.
The first check is sized by the list, and the list is sized by your documentation. Here is how the same claim runs with and without 20 minutes of video:
| Claim stage | With a 20-minute video | Without one |
|---|---|---|
| First 48 hours | Send the video link; start the ALE housing conversation | Start a memory list in a hotel room |
| Week 1 | Itemized list drafted straight from the footage | Digging through card statements and order histories |
| Weeks 2–6 | First contents check based on a full list | Partial list, smaller first check |
| Months 2–4 | Replace items and claim recoverable depreciation | Supplement requests for items remembered late |
| Closeout | Little value left unclaimed | Forgotten items are simply gone |
Already displaced in the OKC metro? The inventory advice below is for next time — right now you need somewhere to live. We place insurance families in furnished homes across Oklahoma City, work with adjusters and TPAs including Alacrity Solutions, and hold a 9.5 out of 10 average across 1,580 verified guest reviews on Airbnb and Vrbo.
See insurance housing options or call/text (405) 870-2146.
Video, App, or Spreadsheet: Which Method Should You Use?
A narrated video home inventory of a typical apartment takes about 20 minutes. A photo-and-spreadsheet inventory of the same rooms usually takes a full weekend, and an unfinished inventory protects nothing.
- Narrated phone video: fastest by far, and it captures condition and context (the inside of drawers, the fullness of closets) that written lists miss. Its weakness is dollar values, which is fine, because pricing happens later, during the claim. A narrated video is typically accepted as documentation of what you owned and its condition.
- Home inventory app: many carriers offer free apps that structure entries item by item, some with barcode scanning. The structure is excellent; the failure mode is abandonment at room two. Treat an app as a phase-two upgrade after the video exists.
- Spreadsheet plus photos: the right tool for high-value categories like tools, instruments, cameras, and jewelry, where serial numbers, appraisals, and receipts matter item by item.
- Receipts folder: it won't serve as an inventory on its own, but keep receipts for anything over roughly $500. They strengthen replacement-cost claims later. Video proves an item existed, receipts prove its value, and the two together move a contents claim fastest.
The best home inventory is the one that exists when the sirens go off. Record the video first, then layer the app or spreadsheet on top when you get a rainy Saturday.
How to Make a Home Inventory Video in 20 Minutes, Step by Step
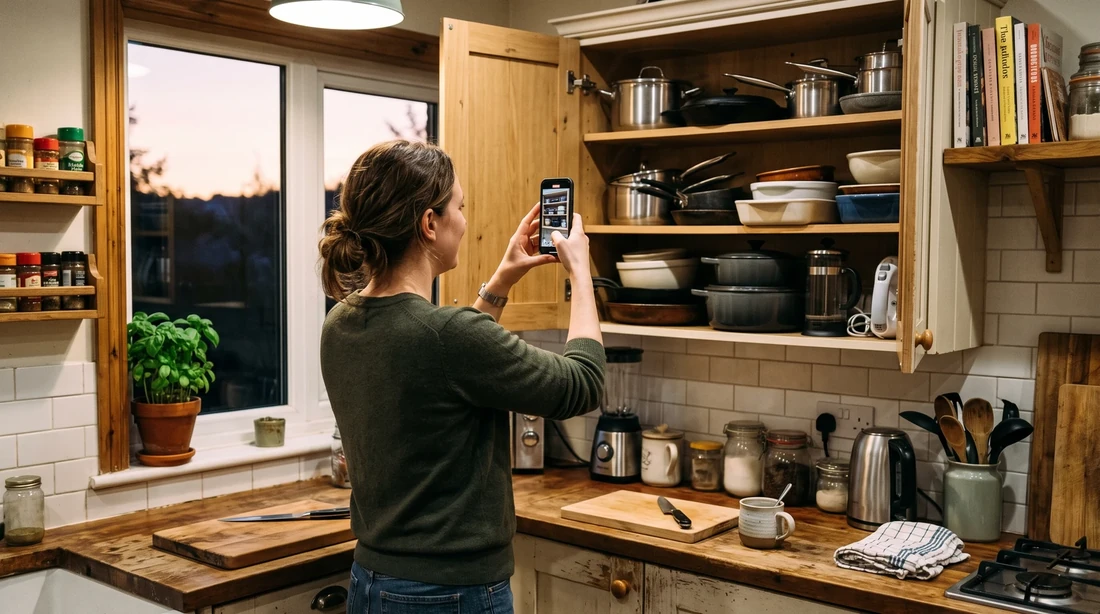
The technique is simple: film slowly, talk constantly, and open everything. Your narration is the metadata. Saying "that's the 65-inch TV we bought in 2024" turns a blurry rectangle in the footage into a claimable item.
Don't aim for pretty. One continuous take per floor is fine. Turn on every light, and don't skip rooms because they're messy, since mess is where value hides.
- Start at your front door and state the date, your name, and your address on camera.
- Walk each room slowly, narrating brands, models, and where you bought big-ticket items.
- Open every closet, drawer, and cabinet, because packed storage is where the value hides.
- Zoom in on serial numbers and model plates for electronics and appliances.
- Film the garage, patio, attic, and any storage unit before you stop recording.
- Upload the video to cloud storage and share the link with someone outside your home.
That last step is the one people skip. A video stored only on a phone that burns with the apartment protects nothing. Cloud backup plus one out-of-town person holding the link means the file survives anything that happens to your address: fire, tornado, or a phone left on the roof of a car. Turn on automatic video backup, and text the link to an out-of-town relative or friend the same day you film.
What Goes on a Room-by-Room Home Inventory Checklist?
Most under-documented value hides in five places: closets, the kitchen, the garage, kids' rooms, and whatever lives under the beds.
| Room | Film this | Commonly missed |
|---|---|---|
| Kitchen | Open every cabinet and drawer; pan across small appliances | Cookware sets, knife blocks, specialty gadgets |
| Living room | Electronics with model plates; furniture from two angles | Cables, controllers, media and book collections |
| Bedrooms | Furniture, bedding, and everything in the closet | Clothing — often the largest single contents category |
| Kids' rooms | Toys, tech, sports gear, school devices | Stored outgrown gear, car seats, strollers |
| Bathroom & laundry | Inside cabinets and the linen closet | Cosmetics and toiletries — they add up fast |
| Home office | Computers, monitors, chair, peripherals | Software licenses; note any employer-owned equipment |
| Garage & outdoor | Tools, mower, bikes, storage bins | Ladders, coolers, camping gear, holiday decorations |
One category deserves its own callout: clothing. Clothing is routinely among the largest single lines in a contents claim. No one piece is expensive; it's hundreds of mid-priced items nobody can list from memory. Film both sides of every closet and narrate the expensive pieces, like coats, boots, and work clothes.
If you have kids, get the storage bins too. Outgrown-but-kept clothes, car seats, strollers, and school-issued devices all show up on real claims, and all of them vanish from memory under stress.
What sits outside the rooms and gets skipped?
Five places sit outside the room-by-room walkthrough and get skipped constantly:
- Storm shelter or safe room: plenty of Oklahoma shelters double as storage for camping gear, emergency radios, and document boxes. Film inside it like any other closet.
- Off-site storage unit: many policies cover personal property away from home, but often at a reduced limit, commonly a fraction of your full contents limit. Film the unit and ask your agent what your off-premises cap is.
- Your car: personal items stolen from or destroyed in a vehicle typically fall under your renters or homeowners policy, not your auto policy. The golf clubs and car seats in your trunk belong in this inventory.
- Employer-owned equipment: narrate the work laptop and monitor as employer property. It documents your home-office setup for the housing conversation without accidentally claiming gear that isn't yours.
- Roommates' belongings: each roommate's policy covers only their own things. If you share a place, narrate whose is whose, or better, have each roommate film their own 10 minutes.
How Do Sub-Limits, Appraisals, and Scheduling Work for Valuables?
Many policies cap categories like jewelry, watches, firearms, cash, and collectibles at a few thousand dollars each, no matter how large your overall personal property limit is.
These caps are called sub-limits, and they most often bite on theft claims. Your declarations page lists them, and most people discover theirs for the first time during a claim, which is the worst possible moment.
Sub-limits commonly cap the whole category instead of each item. A gun safe holding several firearms, a jewelry box with an engagement ring and two heirloom pieces, or a card collection can each blow past a category cap on their own.
The fix is a scheduled personal property endorsement: an itemized add-on that lists specific items at appraised values, typically requiring a receipt or appraisal per item. For anything a sub-limit would shortchange, film it with the serial number visible, photograph the appraisal, and ask your agent about scheduling it.
One caution cuts the other way. Your inventory video is a map of your valuables. Keep it in private cloud storage, share the link with exactly one trusted person outside your home, and never post any of it publicly.
Does an Inventory Matter for Partial Losses Like Hail, Smoke, and Water?
Wind and hail drive most Oklahoma property claims, more than fire does, and most losses are partial. A partial loss runs on the same room-by-room proof; it just uses fewer rooms of it.
A tornado that peels back the roof over two bedrooms puts rain through everything in those two rooms, and those closets need documentation exactly as a total loss would. A kitchen fire's smoke and soot travel through an entire apartment, and the clean-versus-replace decision on every textile in the unit runs on evidence of pre-loss condition.
Timing matters here too. After a metro-wide hail event, adjusters typically carry heavy caseloads, and the claim file that arrives complete tends to move ahead of the one that trickles in. The same storms backlog OKC contractors for months, which is why repair timelines slip and why the budget headroom in the worked example below matters.
Short partial-loss displacements (a few nights during smoke remediation) often mean a hotel voucher rather than a furnished home. How that works is covered in does renters insurance cover hotel stays.
How Does an Inventory Speed ALE Approval and Temporary Housing?
ALE, the coverage that pays for temporary housing, moves faster when the adjuster can see how your household lived, and your inventory video shows exactly that.
The same footage that proves your contents also proves three bedrooms, a crib in the second one, a dog bed by the door, a desk you work from. That's what "comparable housing" gets measured against. A claim file that clearly shows a household of four with a dog is much harder to scope into a single hotel room for four months.
Comparable also means location. Displacement doesn't have to mean changing your kids' school, and a furnished home in the same part of the metro keeps the morning routine intact. Our homes sit near Lake Hefner, in The Village, and near the Paseo and Plaza districts, and several are dog-friendly. Pet policies are one of the most common points of hotel friction for displaced families; see pet-friendly rentals in OKC.
To be clear, your carrier and adjuster make every coverage decision. An inventory doesn't guarantee an approval. It removes the friction that slows one. If housing gets denied or scoped too small anyway, start with insurance denied temporary housing.
Once housing is approved, the paperwork splits across several parties. Here's who owns what:
| Task | You | Adjuster / carrier | Housing host |
|---|---|---|---|
| Inventory video & contents list | Create and submit | Review and price | — |
| Proof of loss form | Sign and return by the deadline | Provide the form, set the deadline | — |
| ALE budget and duration | Keep every receipt | Approve, extend, adjust | — |
| Housing search | Pick what fits your household | Authorize the rate | Offer options and flexible terms |
| Monthly invoices for the claim file | Forward if asked | Reconcile against the ALE budget | Issue itemized invoices |
| Extensions when repairs slip | Ask early, in writing | Approve added time | Extend month to month |
Direct billing, where the housing provider invoices your carrier directly, happens only with the carrier's or TPA's authorization; otherwise you pay and submit receipts. How that machinery works end to end is covered in how ALE housing companies work.
What Does the Math Look Like? Apartment Fire, Two Kids, $2,800 a Month
This scenario is hypothetical, but the arithmetic is real. Say a kitchen fire displaces a renter and two kids for three months. The renters policy carries $30,000 in personal property, and loss of use is set at 30% of that, a $9,000 ALE budget. Normal rent is $1,450 a month, and ALE typically pays only the costs above that normal baseline.
Path one is an extended-stay suite at $149 a night: 90 nights × $149 = $13,410. Subtract three months of normal rent ($4,350) and the "additional" cost is $9,060. That's the entire ALE budget, gone before counting a single meal. With no real kitchen, restaurant food typically adds another $40 to $60 a day above a family's normal grocery spend.
Path two is a furnished three-bedroom in the ballpark of $2,800 a month: 3 × $2,800 = $8,400. Subtract the same $4,350 baseline and the additional cost is $4,050, less than half the budget, with a kitchen and laundry keeping daily spending close to normal.
| Option | Typical monthly cost | Kitchen & laundry | ALE-countable cost above $1,450 rent |
|---|---|---|---|
| Standard hotel room (~$139/night) | ~$4,170 | None | ~$2,720 plus meals out |
| Extended-stay suite (~$149/night) | ~$4,470 | Kitchenette, shared laundry | ~$3,020 |
| Furnished 3-bedroom (~$2,800/month) | ~$2,800 | Full kitchen, in-unit laundry | ~$1,350 |
Now stretch the same claim to four months, a common slip after spring storm season, when OKC contractors book out. Extended-stay: 120 nights × $149 = $17,880, minus $5,800 in rent baseline = $12,080 additional. That's $3,080 past the $9,000 budget, and the overage is typically yours. Furnished home: 4 × $2,800 = $11,200, minus $5,800 = $5,400 additional, which still leaves $3,600 of headroom for the month nobody planned.
Run the contents side of the same claim, too. Say the family's clothing itemizes at $9,000 replacement cost off the video, and the carrier depreciates it roughly 50% (carriers set depreciation by item age and type). The first check includes $4,500 for clothing, with another $4,500 in recoverable depreciation released against replacement receipts. From memory, that same family might reconstruct $3,500 of clothing, which means a $1,750 first check, and the unremembered items never enter the claim at all. Same closets, roughly $2,750 less up front on one category alone.
For reference, our furnished OKC homes publish from-rates of $225 to $425 a night, with monthly rates on 30+ night stays and up to 35% savings for booking direct on stays of 4+ nights. If your adjuster just approved housing, start here. The full post-fire playbook is in temporary housing after a house fire.
When Don't You Need Any of This?
Not every loss needs a furnished home, and not every household needs more than a phone video.
If the damage lands near your deductible, filing may not even make sense, and no inventory changes that math. If repairs take a night or two, the carrier's hotel voucher is the right answer; take it and keep the receipts. Single traveler, points loyalty, short stay: a hotel wins.
The same goes for paid inventory services and formal appraisals. They earn their fee for real collections, scheduled jewelry, and estates. For a typical apartment or house, the 20-minute video plus a receipts folder covers you.
The math flips when the timeline stretches. Displacement of 30+ nights is usually the tipping point. That's when real bedrooms, a kitchen, laundry, a yard for the dog, and staying in your kids' school zone turn into budget protection as much as comfort. When you're there, see our extended stays.
Terms You'll Hear, Decoded
- Additional Living Expenses (ALE): pays the extra cost of living elsewhere, meaning the amount above what you normally spend instead of your whole housing bill.
- Loss of use: the section of your policy that contains ALE; commonly set as a percentage of your dwelling or personal property limit.
- Actual cash value (ACV): replacement cost minus depreciation, typically the size of the first contents check.
- Replacement cost value (RCV): what buying the item new costs today; the gap above ACV is paid as recoverable depreciation once you replace the item.
- Sub-limit: a per-category cap, often on jewelry, firearms, or cash, that applies regardless of your overall contents limit.
- Proof of loss: the sworn statement summarizing your claim. Carriers often set a firm deadline for returning it.
- Direct billing: the housing provider invoices your carrier or TPA directly, only with their authorization.
Your Next Steps
- Pull up your policy's declarations page tonight and find three numbers: your personal property limit, your loss-of-use line, and any sub-limits on jewelry, firearms, or collectibles.
- Record the 20-minute video this weekend, upload it to cloud storage, and share the link with someone outside your home. Then pull receipts or appraisals for anything a sub-limit would shortchange.
- If a loss has already displaced you in the OKC metro, skip straight to housing: insurance housing options or call/text (405) 870-2146.
For consumer claim questions in Oklahoma, the Oklahoma Insurance Department offers free help, and the City of Oklahoma City publishes severe-weather preparedness resources.
Bottom Line
A home inventory is the proof behind your contents payout, and the same video helps your adjuster see what comparable housing means for your household. Twenty minutes with a phone, uploaded to the cloud and shared with one person outside your home, covers most households. Add receipts and appraisals for anything a sub-limit would cap, and re-film once a year.
This guide is general information, not insurance or legal advice; your carrier makes all coverage decisions.